
By Ken Bianchi September 22, 2026
Indiana retailers making taxable retail sales generally need an active Indiana registered retail merchant certificate. The RRMC normally operates on a two-year renewal cycle, but renewal depends on tax compliance. Missing returns or unpaid tax can prevent renewal or support revocation, requiring the merchant to cure the account before resuming taxable retail transactions.
| Question | Current Indiana rule |
| What is the RRMC? | Indiana’s certificate for a registered retail merchant making retail transactions |
| Who issues it? | Indiana Department of Revenue |
| Registration fee | $25 for each place of business |
| Normal validity period | Two years |
| Automatic renewal? | Generally, when required returns and listed taxes are current |
| Can unpaid tax affect renewal? | Yes |
| Can an RRMC be revoked? | Yes, under statutory grounds |
| Where are returns and payments handled? | Generally through INTIME |
| Can a revoked certificate be restored? | Yes, after applicable filing and liability requirements are resolved |
Indiana Registered Retail Merchant Certificate: What It Is and Why It Matters
A Registered Retail Merchant Certificate, usually called an RRMC, is issued after a business registers for Indiana retail sales tax. The Indiana Department of Revenue’s current sales-tax guidance explains that this registration allows a merchant to legally conduct retail sales in Indiana and that an RRMC is required for each retail business location.
The RRMC is not the same thing as an EIN, an Indiana LLC registration, a local vendor permit, or a merchant-processing account. A card processor may let a store accept Visa or Mastercard transactions, but that payment relationship does not replace the Indiana DOR retail merchant certificate or the obligation to file and remit Indiana sales tax.
Indiana’s statewide sales-tax rate is currently 7%. The certificate concerns registration to conduct retail transactions and administer sales tax; it does not by itself determine whether every individual sale is taxable.
Who Needs an Indiana Registered Retail Merchant Certificate?
Businesses with taxable retail sales
Indiana businesses selling tangible personal property and other taxable items or services generally need sales-tax registration and an RRMC. That covers ordinary physical retailers and, where their transactions are taxable, businesses such as restaurants.
Businesses selling only non-taxable services
Not every Indiana business needs an RRMC. DOR states that Indiana does not generally tax services, and a service provider that does not sell tangible personal property or provide taxable services may not have a sales-tax registration obligation merely because it operates a business.
Remote and ecommerce sellers
A seller with physical presence in Indiana generally must collect and remit Indiana sales tax on taxable sales. A remote seller without physical presence must register when gross revenue from sales into Indiana exceeds $100,000 in the current or preceding calendar year. Indiana removed its former 200-transaction economic-nexus threshold effective January 1, 2024.
Multiple locations
Indiana requires separate registration and an RRMC for each place of business. Businesses under the same FEIN may obtain permission to consolidate sales-tax filings, but consolidated filing does not eliminate the location-level certificate requirement.
Temporary or seasonal sellers
The general RRMC statute does not create a broad exemption simply because a seller operates seasonally or temporarily. A merchant planning taxable Indiana retail transactions should determine its registration requirement before selling.
How to Register for an Indiana Retail Merchant Certificate
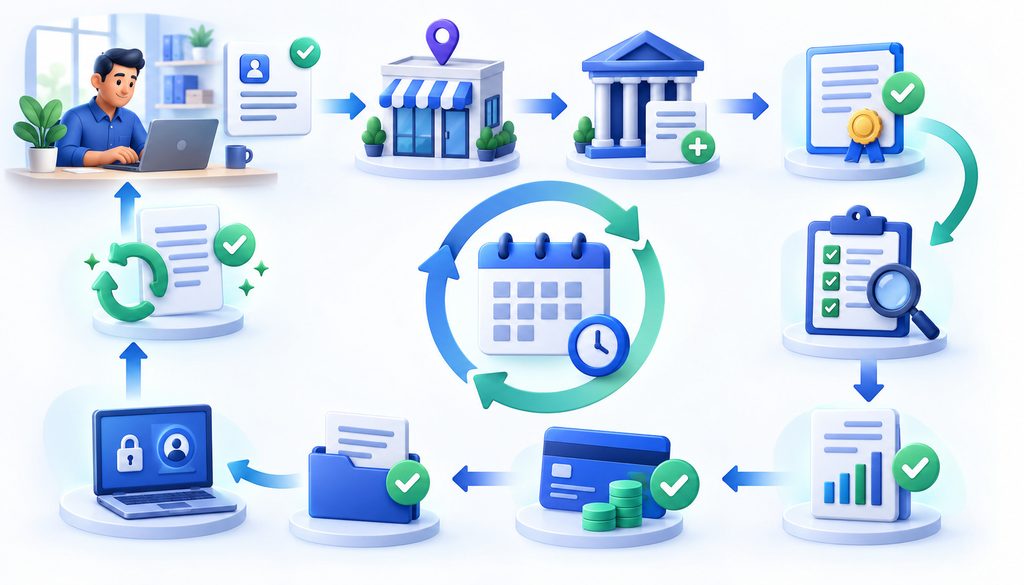
Current DOR guidance directs new businesses to register through INBiz using the Business Tax Application process. Once registration is processed, DOR issues the RRMC. Established businesses can use INTIME for many later account-management functions, including adding tax types or locations.
DOR’s BT-1 checklist calls for information including the business’s legal name, FEIN where applicable, entity type, mailing and business addresses, NAICS code, responsible-officer information, DBA, and the tax types being registered.
Registration checklist
- Confirm that the business will make taxable retail sales.
- Gather the required entity and identification information.
- Complete the current DOR registration through INBiz.
- Identify every Indiana business location that requires registration.
- Pay the applicable $25 fee for each location.
- Confirm that the sales-tax account has been established.
- Obtain the RRMC for each registered location.
- Establish and retain appropriate INTIME access.
- Confirm the filing frequency assigned to the account.
- Calendar the first required sales-tax return—even if activity may be zero.
DOR’s January 2026 INTIME guide says renewed RRMCs are delivered electronically through INTIME under the portal’s letters area.
Indiana RRMC Registration Fee
Indiana Code sets the registration fee at $25 for each place of business listed on the application. Adding a new place of business requires the applicable registration fee for that location.
That is different from ordinary renewal. A compliant RRMC is renewed at no cost under the statute.
An older DOR delinquent-merchant FAQ separately references a $25-per-location reinstatement fee after delinquency. Because current general RRMC guidance focuses on curing returns and liabilities and does not restate that fee, a merchant facing reinstatement should follow the amount shown on its current DOR notice or INTIME account rather than assume a historical fee automatically applies.
RRMC Renewal Indiana: How the Renewal Cycle Works
For normal RRMC renewal Indiana rules, the certificate remains valid for two years after original issuance or renewal. If the merchant has filed the required returns and remitted the listed taxes it currently owes, Indiana Code directs DOR to renew the certificate within 30 days after expiration at no cost.
DOR describes compliant renewals as automatic. The statute also contains a special rule: if DOR sends a nonrenewal notice because returns or liabilities are outstanding and the merchant files all returns and pays the outstanding liability before expiration, the resulting renewal is for one year, rather than the ordinary two-year period.
| Issue | Effect on renewal |
| All returns filed | Required, but filing alone is not enough if required tax remains unresolved |
| Tax paid | Supports normal renewal when other requirements are current |
| Outstanding assessment | Depends on its procedural status; review the specific notice rather than treating every proposed assessment as a final delinquency |
| Unfiled returns | Can block renewal |
| Active payment arrangement | Current DOR guidance says renewal may proceed after the required down payment in an established plan is fulfilled and other returns/liabilities are clear |
| Certificate already revoked | Cure and reinstatement are required; do not rely on the old certificate |
| Business closed | Close the tax account instead of allowing recurring filing obligations to continue |
Why an Indiana RRMC Renewal Can Be Blocked
Indiana Code says DOR may not renew an RRMC when the merchant has not filed all required returns and remitted listed taxes it is currently obligated to file or pay. For this renewal mechanism, DOR must notify a delinquent merchant at least 60 days before the certificate expires.
That is nonrenewal, not necessarily the same thing as revocation. An account can also be closed because a business has ceased operations, while an assessment establishes a claimed tax liability and a tax warrant is a later collection device. Those events should not be used interchangeably.
RRMC Revoked for Unpaid Sales Tax: What Triggers Revocation?
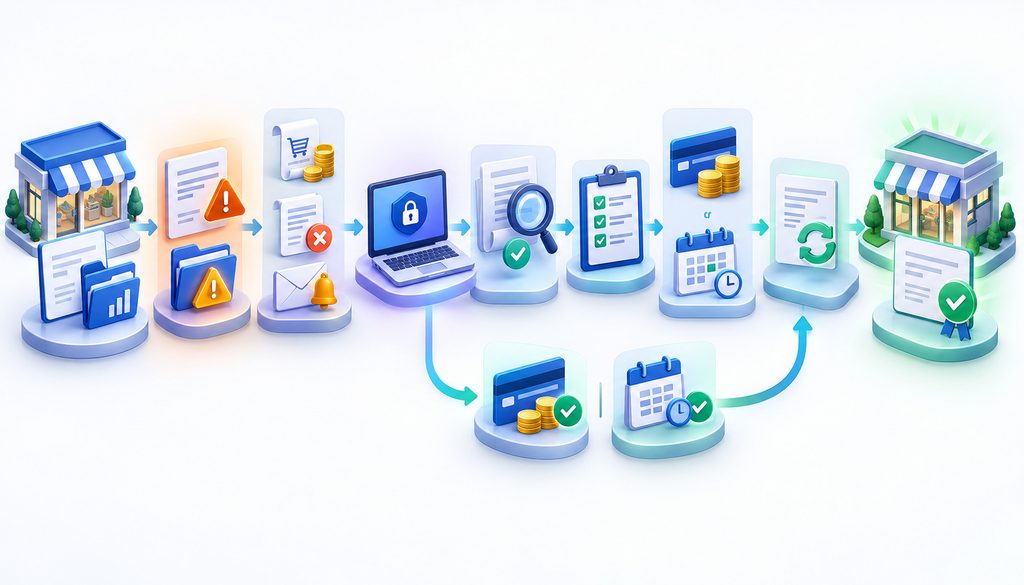
When an RRMC is revoked for unpaid sales tax, the legal framework is broader than “one payment was late.”
Indiana Code permits DOR, after at least five days’ notice, to revoke an RRMC for good cause. Express grounds include failure to file a required sales-tax or other trust-tax return and failure to remit tax collected for the state in trust. The statute also lists default on a qualifying payment plan entered before the most recent certificate renewal as a possible ground.
A separate subsection permits revocation where, for six months, the holder fails to file required sales-tax returns or fails to report any sales/use-tax collection on the returns it files.
DOR consequently maintains a public list of merchants whose certificates have been revoked for delinquent sales or withholding-tax nonpayment or nonfiling.
How the Indiana DOR Notifies You Before or After Revocation
The notice depends on the stage of the problem.
For renewal-based delinquency, the RRMC statute requires notice at least 60 days before expiration. For revocation for good cause under IC 6-2.5-8-7, the statute provides at least five days’ notice.
A separate proposed tax assessment generally carries a 60-day protest period. If the liability is neither paid nor protested, DOR’s collection process can proceed to a Demand Notice, which generally provides another 20 days before a tax warrant is issued.
INTIME allows taxpayers to view DOR letters, respond to notices, and communicate with the department. The January 2026 guide specifically says RRMC documents appear under “View Letters.”
Can You Keep Selling If Your RRMC Is Revoked?
No merchant should treat an old paper certificate as continuing authority after DOR has revoked or suspended it.
Indiana Code § 6-2.5-9-2 states that a retail merchant making a retail transaction without having obtained the required certificate or renewal, or after the certificate has been revoked or suspended, commits a Class A misdemeanor. That is the statute’s language; it does not mean every delinquent payment automatically creates a criminal case.
If Your Certificate Has Been Revoked
Do not assume that the old certificate remains usable while you negotiate with DOR. Confirm the current status, read every notice, address missing returns and liabilities, identify any protest deadline, and obtain confirmation that the RRMC is active again before relying on it for taxable retail sales.
How to Get an Indiana Retail Merchant Certificate Reinstated
A practical cure workflow is:
- Log in to INTIME and review the affected sales-tax account.
- Identify every unpaid period, missing return, notice, assessment, and payment-plan issue.
- File all outstanding required returns, including required zero returns.
- Review whether any assessment is disputed or simply unpaid.
- Pay the balance or determine whether the account qualifies for a DOR payment arrangement.
- If an assessment is disputed, file a proper protest within the applicable 60-day deadline.
- Respond to DOR requests and upload supporting documents through INTIME where appropriate.
- Meet the conditions DOR identifies for reinstatement.
- Verify that a renewed or reinstated RRMC has actually been generated.
- Resume taxable retail transactions only after the certificate is active.
Current DOR sales-tax guidance says that when liabilities are resolved—or an eligible payment plan has been established as required—and no returns remain unfiled, a revoked RRMC can be reinstated. DOR states that a revoked certificate is renewed after a seven-day waiting period; its delinquent-merchant FAQ describes generation overnight following that period.
INTIME Sales Tax Indiana: What You Can Do in the Portal
For INTIME sales tax Indiana administration, the portal is the working hub after registration. DOR currently supports filing returns, making payments, paying bills, establishing eligible payment plans, responding to letters or notices, secure messaging, viewing balances, and uploading documents.
INTIME also displays DOR correspondence and electronically delivers renewed RRMCs. New-business registration, however, is currently directed through INBiz, so the two systems serve different parts of the lifecycle.
Can You Use a Payment Plan to Fix an RRMC Problem?
Potentially. DOR currently says business tax liabilities generally must exceed $500 to qualify for an online payment plan. Maximum terms range from 12 months for liabilities of $501–$1,000 to as much as 36 months for balances above $5,000.
A plan does not erase penalties or interest. DOR states that interest continues until the liability is paid, and default can lead to further collection.
For the RRMC specifically, current DOR guidance says renewal can occur after the required down payment in an established payment plan is fulfilled, provided no additional liabilities or unfiled returns remain. That is not the same as saying that clicking “set up payment plan” automatically restores a revoked certificate.
What If You Disagree With the Tax Assessment?
Disputing a tax bill and being unable to pay an agreed tax bill are two different problems.
DOR currently allows a taxpayer 60 days from a proposed assessment to submit a written protest. The deadline is statutory and DOR says it cannot be extended. The protest uses State Form 56317 with the written explanation and supporting material; DOR also provides electronic protest functionality through INTIME.
An older delinquent-merchant FAQ still refers to 45 days. That older statement conflicts with DOR’s current Appeals page and current collection guidance, both of which use 60 days, so merchants should follow the current assessment notice and 60-day rule.
A payment plan addresses how an accepted liability will be paid. A protest addresses whether the proposed liability is correct.
How Tax Warrants Fit Into the Process
A tax warrant is a collection tool, not another name for RRMC revocation.
DOR’s published collection sequence generally moves from a proposed assessment to a Demand Notice and then, if unresolved, to a tax warrant. The Demand Notice generally provides 20 days to pay or establish reasonable cause. When filed with the county clerk, the warrant becomes a judgment lien and public record; it is not an arrest warrant.
A business can therefore have both a collection problem and a certificate-status problem, but the two should be tracked separately.
Why Collected Sales Tax Should Never Be Treated as Spendable Revenue
Indiana law expressly treats sales tax collected for the state as tax held in trust and can impose personal responsibility on individuals who have the duty to remit it.
Operationally, the problem often begins when an owner sees a processor payout as available cash. The deposit can include merchandise revenue and collected tax, while also being reduced by fees, refunds and other adjustments.
A cleaner system records the sales-tax liability when the sale occurs and reserves enough cash to remit it instead of waiting until the filing deadline.
How to Reconcile Card-Processing Deposits Against Indiana Sales-Tax Filings
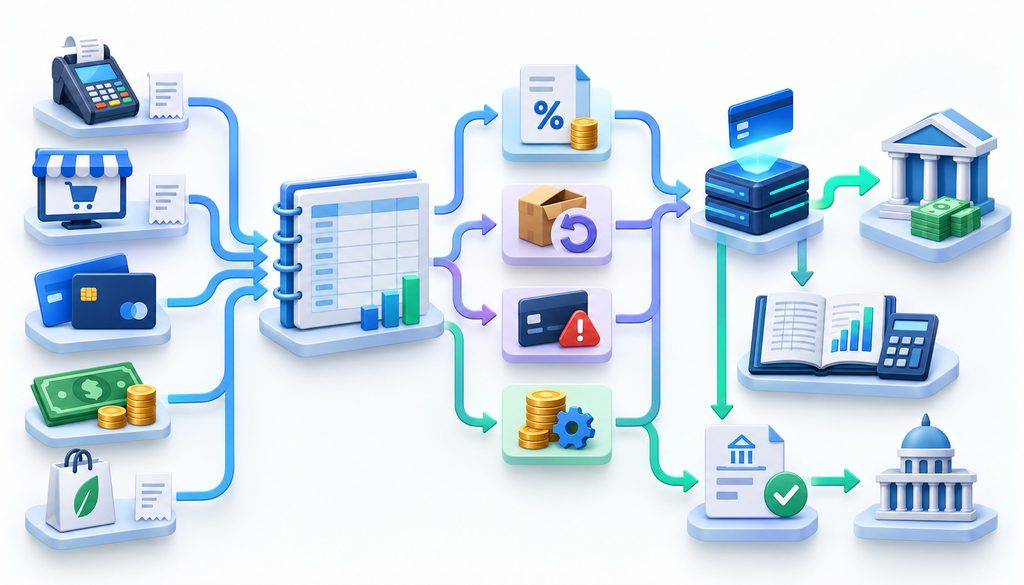
Processor deposits are not the same as taxable sales. A processor payout may be reduced by fees, refunds, chargebacks, reserves or settlement timing.
Retailers using several payment channels should also understand how credit cards and digital payment methods create different transaction and settlement records, because POS sales, ecommerce transactions, mobile payments and bank deposits may not all appear in the same report or settle on the same schedule.
Monthly reconciliation workflow
- Pull gross sales from the POS and ecommerce systems.
- Separate taxable, exempt and non-taxable sales.
- Reconcile the sales tax actually collected.
- Compare gross card transactions with processor reports.
- Account separately for refunds and chargebacks.
- Match processor payouts to bank deposits.
- Record processing fees separately instead of netting them against sales.
- Compare taxable sales with the figures prepared for the Indiana return.
- Investigate differences before filing.
- Retain the reconciliation with the tax records.
The accounting system should reconcile gross transactions to settlement activity, not treat net bank deposits as gross receipts.
Example: $50,000 in Gross Monthly Sales
Assume a retailer records $50,000 in merchandise sales before refunds. Of that amount, $5,000 is properly exempt or non-taxable and $45,000 is initially taxable.
The store then refunds $1,000 of taxable merchandise plus $70 of associated Indiana sales tax. Taxable sales after that refund are $44,000, producing $3,080 of sales tax at Indiana’s current 7% statewide rate.
| Reconciliation item | Hypothetical amount |
| Gross merchandise sales | $50,000 |
| Exempt/non-taxable sales | $5,000 |
| Taxable sales before refund | $45,000 |
| Taxable merchandise refund | $1,000 |
| Taxable sales after refund | $44,000 |
| Sales tax collected after refund | $3,080 |
| Customer refund including tax | $1,070 |
| Processor fees | $1,250 |
| Net processor deposits, assuming all transactions were card-based | $50,830 |
The $50,830 bank deposit is neither the $50,000 merchandise-sales figure nor the $44,000 taxable-sales figure. Copying it onto an ST-103 would therefore produce the wrong sales-tax reporting base.
RRMC Rules for Ecommerce and Online Sellers
Indiana ecommerce obligations depend on presence, revenue and selling channel.
An Indiana-based seller with physical presence generally must register and collect applicable tax. An out-of-state seller crosses Indiana’s economic-nexus threshold when gross revenue from sales into Indiana exceeds $100,000 in the current or preceding calendar year.
Marketplace sales require another distinction. Indiana treats the marketplace facilitator as the retail merchant for facilitated transactions. A seller making sales only through a marketplace facilitator generally does not have to register and file Indiana sales-tax returns solely for those marketplace sales.
If that seller is otherwise required to register because it has physical nexus or qualifying direct sales, DOR instructs it to report facilitated marketplace sales as exempt sales on its Indiana return. Marketplace transactions do not simply eliminate obligations created by the seller’s own direct channel.
What If You Have More Than One Indiana Location?
Each Indiana place of business requires its own RRMC and the $25 registration fee. A new location therefore is not covered simply because the business already has an RRMC at another address.
Businesses operating multiple locations under the same FEIN can request consolidated sales-tax filing through INTIME or, where necessary, Form BT-1C. The individual location registrations still matter even when the reporting is consolidated.
Do Not Let a Closed Business Keep Filing Problems Alive
Stopping operations does not automatically close an Indiana sales-tax account.
DOR says businesses can close tax accounts through INTIME. A business without an INTIME account can submit Form BC-100. If the account is not properly closed, DOR may continue issuing estimated tax bills.
File required final returns and complete the closure. Until an active trust-tax account is properly closed, a period with no sales may still require a zero return; DOR specifically instructs registered trust-tax taxpayers to file $0 returns when there is no activity.
Common Indiana RRMC Mistakes
Common problems include assuming LLC formation includes sales-tax registration; ignoring an expired or revoked certificate; skipping required zero returns; spending collected sales tax; reconciling only net bank deposits; overlooking DOR notices; assuming a payment plan automatically restores the RRMC; filing without paying; paying without filing the return; continuing taxable sales before reinstatement is confirmed; and abandoning the tax account when a business closes.
Many of these are process problems rather than calculation problems. A monthly close checklist covering returns, liabilities, INTIME correspondence and processor reconciliation can catch them before the next certificate renewal.
FAQs
What is an Indiana Registered Retail Merchant Certificate?
It is the DOR certificate issued to a registered retail merchant making Indiana retail transactions and administering applicable sales tax.
Who needs an RRMC in Indiana?
Generally, merchants making taxable Indiana retail transactions and remote sellers that meet Indiana’s applicable nexus requirements. Businesses providing only non-taxable services may not need one.
How much does an Indiana retail merchant certificate cost?
The statutory registration fee is $25 for each place of business. Normal compliant renewal is free.
How often does an RRMC renew?
The normal certificate period is two years. A special statutory one-year renewal can apply when a merchant receives a delinquency-based nonrenewal notice and fully cures before expiration.
Can Indiana refuse to renew my RRMC?
Yes. Required returns and listed taxes must be current under the renewal statute.
Can DOR revoke my certificate for unpaid sales tax?
Yes. Failure to remit tax collected for the state is expressly listed as potential good cause for revocation, subject to statutory notice procedures.
Can I keep selling after my RRMC is revoked?
Indiana Code makes conducting retail transactions after revocation or suspension a Class A misdemeanor. Confirm reinstatement before resuming taxable retail sales.
How do I reinstate a revoked Indiana retail merchant certificate?
Clear missing returns and applicable liabilities, or establish a qualifying payment arrangement when available, satisfy DOR requirements and confirm that the new certificate has been generated.
Can I use INTIME to set up a payment plan?
Yes, when the business and liability qualify under DOR’s payment-plan rules.
What if I disagree with the amount Indiana says I owe?
A proposed assessment generally must be protested in writing within 60 days. A payment plan is not a substitute for a protest.
Do online sellers need an RRMC?
Some do. Physical presence and Indiana direct sales can create registration obligations, while remote sellers are subject to the current $100,000 economic-nexus threshold. Marketplace-only sellers receive different treatment.
How should card deposits be reconciled to sales-tax filings?
Start with gross POS or ecommerce transactions, identify taxable and exempt sales, reconcile collected tax and refunds, then bridge gross card activity through fees, chargebacks and settlement timing to the actual bank deposits.
Keeping Your Indiana Registered Retail Merchant Certificate in Good Standing
The safest way to protect an Indiana registered retail merchant certificate is to treat compliance as a monthly accounting workflow rather than a two-year renewal event.
File every required return, remit collected tax, review INTIME correspondence, reconcile gross sales to processor settlements, and investigate account discrepancies before they age into collection problems.
If an assessment, nonrenewal notice or revocation has already occurred, identify which problem actually exists before acting: an unfiled return, unpaid liability, disputed assessment, payment-plan default, tax warrant and revoked RRMC are related but legally distinct events.
This article explains general Indiana sales-tax compliance procedures and is not individualized legal or tax advice. Businesses with disputed assessments, large liabilities, or active enforcement should consider consulting an Indiana CPA, tax professional, or attorney.