
By Ken Bianchi September 22, 2026
An Indiana retailer should remove sales tax only when the purchaser has a valid exemption basis and provides the required documentation—usually a properly completed Indiana ST-105 exemption certificate, or another authorized certificate such as NP-1 where applicable. Tie that evidence to the customer and sale, retain it, and never let cashiers invent an exemption from a verbal claim.
Indiana currently lists Form ST-105, General Sales Tax Exemption Certificate, State Form 49065, revision R7/6-23. One major change matters immediately: Indiana nonprofits no longer use ST-105 for their nonprofit exemption; qualifying Indiana nonprofits use Form NP-1 instead.
| Question | Practical answer |
| Who completes ST-105? | The purchaser claiming a qualifying exemption. |
| Who keeps it? | The seller keeps the certificate supporting the exempt sale. |
| Does ST-105 exempt everything a customer buys? | No. The claimed exemption must apply to the transaction and intended use. |
| Can farmers use it? | Yes, for qualifying agricultural purchases, subject to Indiana’s direct-use rules. |
| Can Indiana nonprofits use it? | Generally no. Qualified Indiana nonprofits now use NP-1. |
| Can resellers use it? | Yes, for qualifying purchases for resale, rental, or lease in the ordinary course of business. |
| Should cashiers decide eligibility from a customer’s statement? | No. Use documented exemption categories and escalation rules. |
| Must exemption records be retained? | Yes. Indiana’s certificate-specific rule requires at least three years after the return due date, with broader record rules potentially requiring longer. |
Indiana ST-105 Exemption Certificate: What Sellers Need to Know
Indiana retailers should use the current Indiana Department of Revenue ST-105 materials when reviewing exemption paperwork, because DOR’s current sales-tax forms page for Form ST-105 identifies the General Sales Tax Exemption Certificate currently in use and also explains that nonprofit and gasoline exemptions have moved to different forms.
The current form allows either a single-purchase or blanket exemption. Indiana law also authorizes DOR to permit blanket certificates covering exempt purchases over a stated period, subject to conditions or restrictions.
A properly accepted certificate matters because IC 6-2.5-8-8 provides that a seller accepting a proper exemption certificate has no duty to collect or remit sales or use tax on that purchase. That protection depends on having the right documentation for a transaction that actually fits the claimed exemption.
DOR’s current form puts the recordkeeping point plainly: “Seller must keep this certificate on file to support exempt sales.”
ST-105 cannot currently be issued for utilities, vehicles, watercraft, aircraft, gasoline, or by nonprofit organizations. Those categories may involve different Indiana forms or procedures.
Who Can Legitimately Use an Indiana ST-105?
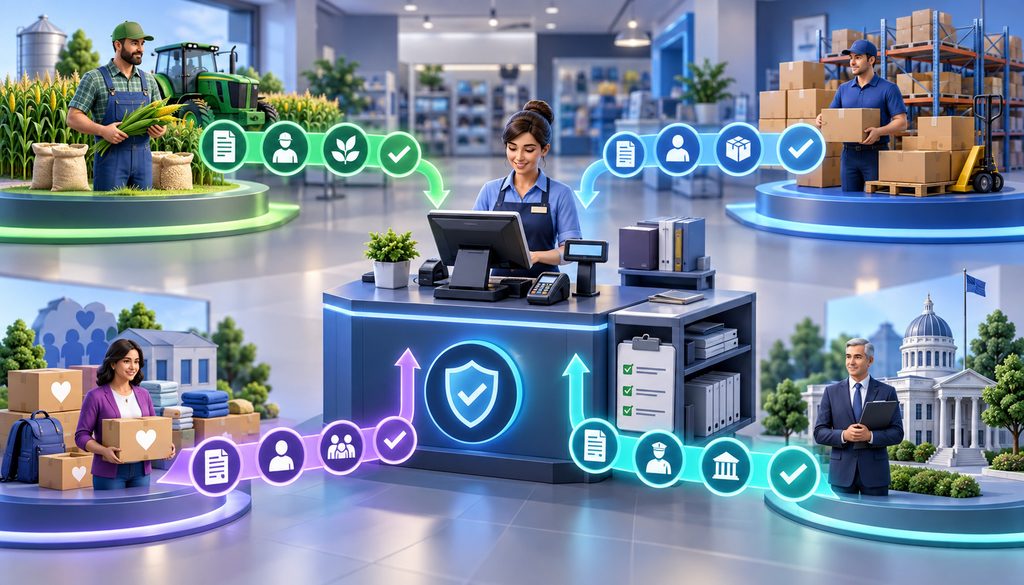
The customer’s identity is only one part of the analysis. A seller also needs to know why this transaction qualifies.
| Buyer type | Typical basis/document | What the seller should verify | Common mistake |
| Reseller | ST-105 resale exemption | Goods are being acquired for qualifying resale rather than consumption | Exempting the reseller’s own supplies |
| Farmer | ST-105 agricultural exemption | Qualifying agricultural activity and qualifying direct use | Treating every farm purchase as exempt |
| Indiana nonprofit | NP-1, not ST-105 | Current vendor-specific NP-1 and organizational purchase | Accepting an obsolete nonprofit ST-105 |
| Indiana government | ST-105 or authorized government evidence | Government entity is the purchaser | Exempting an employee’s personal purchase |
| Federal government | ST-105 or qualifying federal purchasing evidence | Direct federal purchase/payment context | Assuming every employee-held government card is exempt |
An item that is exempt under Indiana law for reasons unrelated to purchaser status is another category entirely. Configure inherently exempt products through product-tax rules rather than turning every purchaser into an “exempt customer.”
What Each ST-105 Exemption Box Means
The current ST-105 Section 4 contains these exemption choices. Direct-pay permits are separate; “direct pay” is not a current ST-105 checkbox.
| Current ST-105 category | What it means operationally |
| Resale | Retailer, wholesaler, or manufacturer acquires property for qualifying resale. |
| Manufacturing | Machinery, tools, or equipment claimed for direct use in direct production. |
| Public transportation | Property claimed as predominantly used—more than 50%—in providing public transportation; the form requests applicable USDOT or permitted substitute identification. |
| Agricultural production | Purchaser occupationally engaged as a farmer claims direct production use for agricultural products for sale. |
| Contractor for exempt project | Contractor claims purchases for an eligible exempt project, such as certain governmental, public-school, or nonprofit work. This is not a blanket contractor exemption. |
| Indiana governmental unit | Qualifying Indiana agencies, cities, towns, municipalities, public schools, and state universities. |
| U.S. federal government | Direct federal government purchase; the form asks for the agency name. |
| Other | A different Indiana-authorized exemption, which the purchaser must explain. |
Resale Exemption: When the Buyer Is Buying Inventory to Resell
Indiana’s resale statute generally exempts tangible personal property acquired for resale, rental, or leasing in the ordinary course of business without changing its form.
That does not turn a reseller into a universally tax-exempt customer. Merchandise acquired as inventory for resale can qualify; shelving, cleaning products, printer paper, or other property that the reseller itself consumes does not become exempt merely because the purchaser has a resale business.
A good POS profile therefore records “resale—qualifying inventory”, not simply “customer pays no tax.”
Farm Exemption Indiana: Why “I’m a Farmer” Is Not Enough
The farm exemption Indiana retailers encounter is based on the particular purchase and its use, not simply the buyer’s occupation. Indiana DOR’s current Agricultural Production Exemptions guidance explains that participating in agriculture does not make every purchase exempt; the property must satisfy the requirements of the applicable agricultural exemption, including direct-production rules where required.
Seed, feed, fertilizer and certain agricultural inputs can qualify when statutory direct-production requirements are met. Agricultural machinery, tools, and equipment can also qualify for direct production, extraction, harvesting, or processing uses. Current law includes special predominant-use and proration rules for qualifying machinery and equipment.
By contrast, general management, administration, marketing, or other nonproduction uses do not automatically qualify. DOR gives examples such as an administrative computer and a refrigerated display counter used for retail sales rather than production.
Example: seed purchased by a commercial producer for qualifying production may fit an agricultural exemption. A computer used solely for the farm’s bookkeeping does not become exempt simply because the purchaser farms.
Where mixed-use agricultural equipment requires an AGQ-100 calculation or another specialized determination, the cashier should not invent a percentage at the register. The current ST-105 instructions direct purchasers that cannot properly claim the full applicable ST-105 exemption to pay tax and use DOR’s refund process where appropriate.
Nonprofit Exempt Purchase Indiana: The Organization May Be Exempt, but the Purchase Still Matters
A nonprofit exempt purchase Indiana retailer processes today generally requires Form NP-1, not ST-105. Older nonprofit ST-105 certificates ceased being valid after December 31, 2023. NP-1 is generated through INTIME for a particular vendor.
Federal tax-exempt or 501(c)(3) status alone does not establish Indiana sales-tax exemption. Indiana’s nonprofit rules also require the purchase to serve the qualifying nonprofit purpose, and DOR says an eligible purchase should be invoiced directly to the organization and paid directly with organizational funds.
That means an employee cannot make a personal purchase tax-free merely by showing a nonprofit affiliation.
Government Purchases and ST-105
Direct purchases by Indiana state and local governmental entities generally receive special exemption treatment. DOR specifically warns that when a state or local government employee personally buys an item, the transaction is not exempt merely because the employee expects reimbursement.
Federal purchases also require attention to who is actually liable for the charge. DOR treats qualifying centrally billed GSA SmartPay accounts differently from individually billed employee accounts.
What Makes an Indiana ST-105 Valid at Checkout?
The current form says all five sections must be completed for the claimed exemption to be valid. Review:
- purchaser name and address;
- required Indiana TID/location number, another state’s tax ID, or an authorized alternative such as an FEIN/SSN for specified categories;
- seller name and address;
- single-purchase or blanket designation;
- description of purchases;
- exemption category and any category-specific information;
- purchaser signature and date;
- printed name and title.
Before Removing Sales Tax
- Identify the certificate or other authorized exemption document.
- Identify the claimed exemption category.
- Check every required field.
- Match the purchaser/customer to the documentation.
- Check whether the merchandise is reasonably consistent with the claimed exemption.
- Associate the document with the customer and transaction.
- Apply the correct POS exemption reason.
- Retain the evidence.
When something is unclear, frontline staff should escalate it rather than interpret tax law from scratch.
When to Refuse an ST-105
| Problem | Accept, correct, or refuse? | Seller action |
| Missing required field | Correct before relying on it | Obtain the missing information |
| Wrong exemption type | Refuse as presented | Ask for appropriate documentation |
| Certificate belongs to another entity | Refuse | Match documentation to actual purchaser |
| Personal purchase | Generally refuse claimed entity exemption | Charge tax unless another exemption independently applies |
| Resale claim for purchaser’s office supplies | Do not treat as resale | Charge tax unless another exemption applies |
| Farm claim unrelated to qualifying production | Do not rely on farm status alone | Charge tax/escalate |
| Old certificate on file | Review rather than reject solely for age | Confirm facts, entity and exemption remain applicable |
The current ST-105 does not impose a general annual expiration date. Do not invent one. But neither should staff assume an old blanket certificate covers a changed legal entity, changed exemption reason, or purchases outside its scope. The obsolete nonprofit ST-105 is a specific exception: those certificates expired for nonprofit use after 2023.
Set Up Tax-Exempt Customer Profiles Instead of Making Cashiers Guess
At the customer level, store entity name, exemption type, certificate reference, certificate date, account/location covered and any restriction notes. An internal review date can be useful, but label it as a company control—not an Indiana statutory expiration date.
At the transaction level, use exemption reason codes, line-level taxable/exempt treatment, restricted override permissions, manager escalation, and a traceable audit trail. Modern checkout systems that preserve transaction histories, access logs, and exception reporting make it easier to determine who applied an exemption or override and connect that action back to the underlying sale.
A regular customer saying, “We never pay sales tax here,” should trigger an account lookup—not the tax-exempt button.
Indiana Sales Tax Exemption at Checkout: A Practical POS Workflow
- Identify the purchaser account.
- Check for current, applicable documentation.
- Confirm the exemption category.
- Review what is being purchased.
- Separate taxable and qualifying exempt lines when necessary.
- Apply the correct reason code.
- Capture new documentation before completing the exemption when practicable.
- Record the certificate/customer reference with the sale.
- Complete the transaction.
- Route exceptions to management or accounting.
Handling Partial Exemptions and Mixed Carts
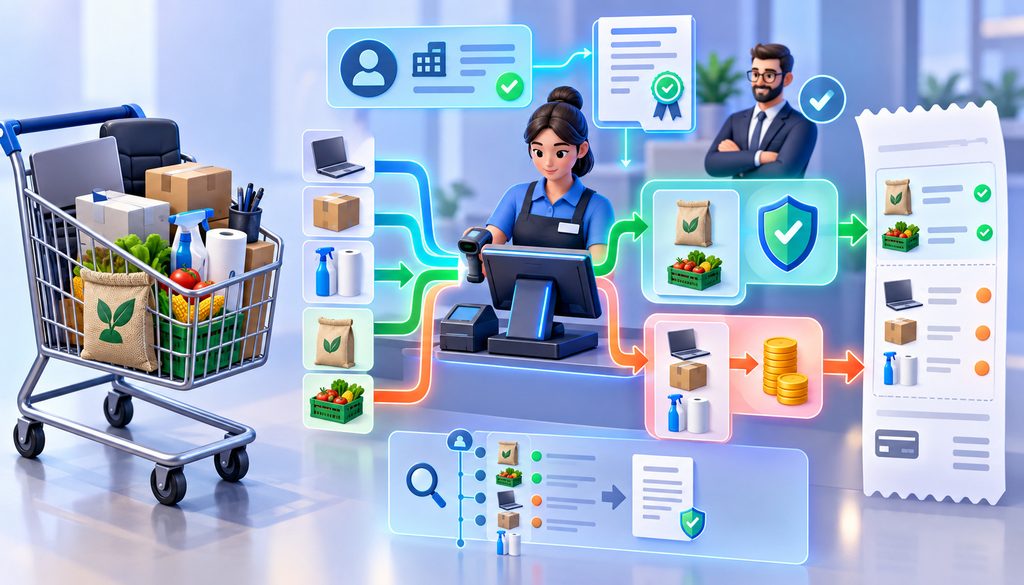
Exemption status can be line-specific. Do not exempt an entire cart simply because one part qualifies.
Consider a reseller with a valid resale certificate:
| Line | Intended use | Treatment under resale claim |
| Merchandise A | Resell unchanged | Exempt |
| Merchandise B | Resell unchanged | Exempt |
| Merchandise C | Resell unchanged | Exempt |
| Printer paper | Reseller’s office use | Taxable |
| Cleaning supplies | Reseller consumes them | Taxable |
| Store shelving | Reseller’s operating equipment | Taxable under the resale claim |
The distinction is whether the property is acquired for qualifying resale, not whether the customer happens to be a reseller.
The same principle applies to farms and nonprofits: review the qualifying purchase and use, not only the buyer’s label.
Can You Keep an ST-105 on File for Repeat Customers?
Yes. The current form includes a blanket-purchase option, and Indiana law expressly permits blanket exemption certificates.
Indiana’s current general ST-105 does not state an annual renewal requirement. Request a replacement when material facts change—such as purchaser identity, registration information, exemption basis, or the kind of purchases covered. A retailer may also schedule periodic internal reviews as a control.
How Long Should You Keep Indiana Exemption Certificates?
45 IAC 2.2-8-12 requires the seller to keep an exemption certificate or other evidence supporting an exempt sale for at least three years after the due date of the tax return on which the exempt transaction was reported.
The broader records statute can require longer retention—for example, while an appeal is pending or when the assessment period has been extended.
Current Indiana sources do not state a special paper-only ST-105 rule. The regulation permits reproduction without changing the certificate’s wording or content, and DOR’s current Audit Manual recognizes electronic records. For digital storage, keep a complete, legible and retrievable copy tied to the proper customer and transaction.
Exemption Certificate Audit Indiana: What the Auditor Will Want to See
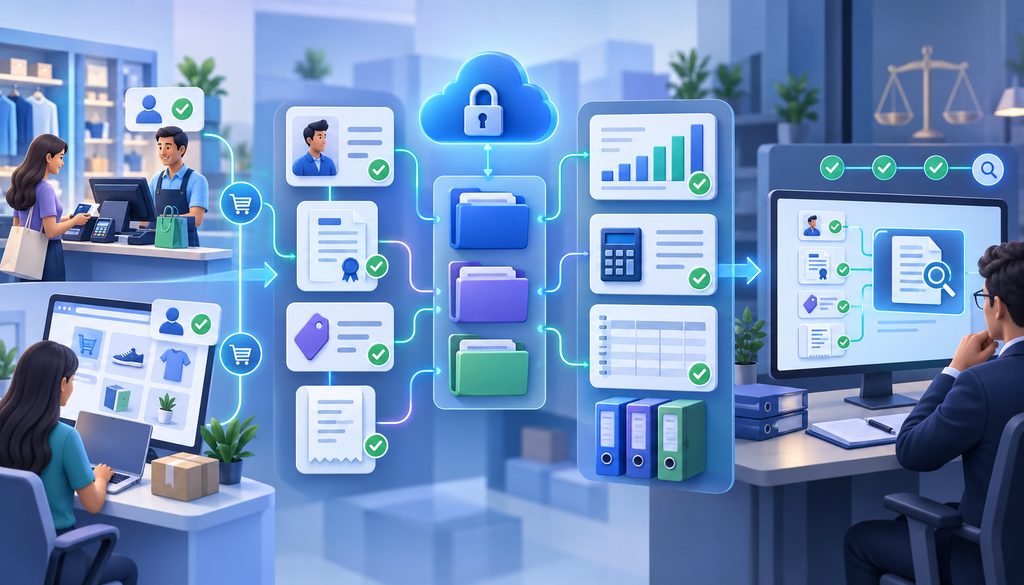
An exemption certificate audit Indiana merchant faces will depend on its facts, but DOR’s Audit Manual identifies records such as invoices, register tapes or POS records, sales reports and journals, exemption certificates, direct-pay permits and other documentation supporting excluded or exempt sales.
The operational goal is traceability:
exempt-sale report → customer → invoice → exemption reason → supporting certificate.
A drawer of certificates with no customer IDs is much less useful than a searchable file tied to actual transactions.
Why Missing Exemption Documentation Can Become the Seller’s Tax Bill
Indiana generally presumes retail sales taxable unless an exemption can be established. A properly completed exemption certificate relieves the seller of collection responsibility for the qualifying purchase; unsupported exempt sales can become audit adjustments.
But “missing certificate = automatic irreversible assessment” is too broad. Indiana law gives a seller that accepted an incomplete certificate 90 days after the sale to obtain a fully completed certificate or the missing data.
If DOR later asks that seller to substantiate that incomplete certificate, the statute provides 120 days after the request to obtain a complete certificate or prove the exemption by other means.
DOR’s Audit Manual also contemplates additional documentation through its audit process. That is a cure opportunity, not permission to ignore documentation at checkout.
What to Do About Past Exempt Sales With No ST-105 on File
Use a controlled cleanup rather than mass-producing forms:
- Export exempt transactions by customer.
- Group them by claimed exemption reason.
- Separate ST-105 transactions from NP-1, marketplace and other categories.
- Identify missing or incomplete records.
- Contact customers for legitimate supporting documentation.
- Match evidence to the purchaser and relevant transaction dates.
- Flag purchases whose exemption cannot be substantiated.
- Quantify potential exposure.
- Escalate material unresolved amounts to an Indiana tax professional.
- Preserve the cleanup report and supporting correspondence.
Never backdate or fabricate an exemption certificate.
Can You Get an ST-105 After Checkout?
Indiana expressly provides a 90-day completion period for an incomplete certificate. During an audit, a seller that had accepted an incomplete certificate has 120 days after DOR’s substantiation request to complete it or prove the exemption another way.
Those provisions should not be rewritten as “you can always collect a certificate later.” A seller that had no documentation at all does not have an unlimited statutory safe harbor, and the purchaser still must have qualified when the transaction occurred.
Accepting Exemption Certificates in an Ecommerce Store
Remote sellers have the same basic Indiana exemption-documentation obligations as other registered retail merchants. DOR says they must obtain an Indiana exemption certificate or an accepted Streamlined Sales Tax certificate when appropriate.
Build an approval workflow: customer applies, uploads documentation, staff verifies it, the account receives the appropriate exemption code, and checkout applies that status only to authorized users and qualifying lines.
Do not provide a guest-checkout checkbox that simply says “tax exempt.”
Marketplace Orders and Exemption Documentation
Marketplace-facilitated transactions require a different control because the marketplace facilitator generally acts as the retail merchant for Indiana collection purposes. DOR also permits a marketplace facilitator to issue a blanket ST-105 to a marketplace seller using the “Other” category for marketplace sales.
Keep marketplace statements and reconciliation records rather than assuming your ordinary direct-sale certificate workflow applies unchanged.
A Better Exemption Workflow for Wholesalers and Distributors
High-volume B2B sellers should centralize certificate intake rather than letting every salesperson approve exemptions independently.
Index certificates by customer ID, legal entity, exemption category, and covered account or location, while restricting manual tax overrides and running exception reports for unsupported exempt sales.
Businesses operating several stores should also make sure their multi-location POS setup keeps customer records, permissions, and reporting synchronized across locations so a certificate approved at one location is not inconsistently handled elsewhere.
A periodic review is sensible internal governance even where Indiana does not mandate annual ST-105 renewal.
How the Customer Pays Does Not Make the Sale Tax-Exempt
A business credit card, ACH payment, check or purchase order does not by itself establish an exemption.
Government cards require more nuance. DOR recognizes directly billed Indiana state procurement arrangements and qualifying centrally billed federal GSA SmartPay accounts as evidence in circumstances described in its government bulletin; individually billed employee accounts generally do not receive that treatment simply because the card is government-branded.
Taxability follows the purchaser, transaction, use and required documentation—not an ordinary payment method.
Reconcile Exempt Sales Before Filing the Indiana Sales-Tax Return
Each month:
- Pull gross sales.
- Separate taxable and exempt sales.
- Group exemptions by reason code.
- Confirm supporting certificates.
- Investigate manual overrides.
- Review mixed transactions.
- Reconcile POS exemption totals to accounting records.
- Retain the reconciliation with the period’s tax records.
| Exemption category | POS exempt sales | Certificates on file | Exceptions to resolve |
| Resale | $_____ | _____ | _____ |
| Farm/agricultural | $_____ | _____ | _____ |
| Nonprofit/NP-1 | $_____ | _____ | _____ |
| Government | $_____ | _____ | _____ |
| Other verified exemption | $_____ | _____ | _____ |
That routine turns certificate management into a monthly control instead of an audit emergency.
Common ST-105 Mistakes Indiana Retailers Make
Common failures include accepting blank certificates; accepting no stated exemption reason; using obsolete nonprofit ST-105s; assuming every farm purchase qualifies; allowing resale treatment for items the buyer consumes; letting cashiers override tax without evidence; treating a corporate card as proof; losing certificates; failing to connect certificates to customer accounts; ignoring mixed carts; and waiting for an audit before reconciling exempt-sales reports.
Four Real-World Checkout Examples
- Farmer with a mixed purchase: The customer presents an agricultural ST-105. Staff applies it only to lines supported by the qualifying agricultural use and escalates uncertain mixed-use equipment instead of exempting the cart because the buyer farms.
- Nonprofit employee: An employee says the charity is tax-exempt. The cashier checks the organization account for a vendor-specific NP-1 and verifies the transaction is directly an organizational purchase rather than accepting an old nonprofit ST-105.
- Reseller with inventory and supplies: Goods bought for resale are coded to the resale exemption. Printer paper and cleaning supplies used by the reseller remain taxable under that resale claim.
- Audit identifies $40,000 of unsupported exempt sales: Accounting exports the transactions, matches customers to existing documents, requests legitimate missing evidence, uses Indiana’s available substantiation procedures where applicable and quantifies whatever remains unresolved.
FAQs
What is an Indiana ST-105 exemption certificate?
It is Indiana’s General Sales Tax Exemption Certificate used for many qualifying purchaser- or use-based exemptions.
Who can use an ST-105 in Indiana?
Current uses include qualifying resale, manufacturing, public transportation, agriculture, exempt-project contractor, Indiana government, federal government and other authorized exemptions shown on the form. Nonprofit organizations generally use NP-1 instead.
Can farmers use ST-105?
Yes, when the purchase meets the applicable agricultural exemption. Farmer status alone is insufficient.
Can nonprofits use ST-105 for every purchase?
No. Qualified Indiana nonprofits now generally use NP-1, and qualifying purpose and purchasing requirements still apply.
Can a reseller use ST-105 for supplies?
Not under the resale exemption merely because it operates a resale business. The property must satisfy the resale rule.
How long must I keep Indiana exemption certificates?
At least three years after the due date of the return reporting the transaction under the certificate-specific regulation, and longer when broader record-retention rules require it.
Can I accept an ST-105 after the sale?
Indiana has specific 90-day and audit-stage rules for completing incomplete certificates. Do not interpret those rules as an unlimited right to create documentation after the fact.
Can my cashier decide whether a customer is exempt?
A cashier can follow a documented verification procedure, but uncertain eligibility should go to management or accounting rather than be decided from a customer’s verbal claim.
Can I keep a blanket ST-105?
Yes, where the blanket exemption appropriately covers the repeat purchases. The current ST-105 has a blanket option, and Indiana law authorizes blanket certificates.
Keeping Indiana ST-105 Exemption Documentation Audit-Ready
The safest Indiana st-105 exemption certificate process is not “collect a form and forget it.” Build a chain that shows who bought what they bought, why the transaction was exempt, which document supported it, and where that document can be retrieved.
Use customer-level approval, transaction-level exemption codes, line-level treatment for mixed carts, monthly reconciliation and controlled exception handling. That gives a cashier a simple process today and gives accounting a defensible trail years later.
This article explains general Indiana sales-tax exemption procedures and is not individualized tax or legal advice. Businesses facing an audit, disputed exemption, or material historical exposure should consider consulting an Indiana CPA, tax professional, or attorney.